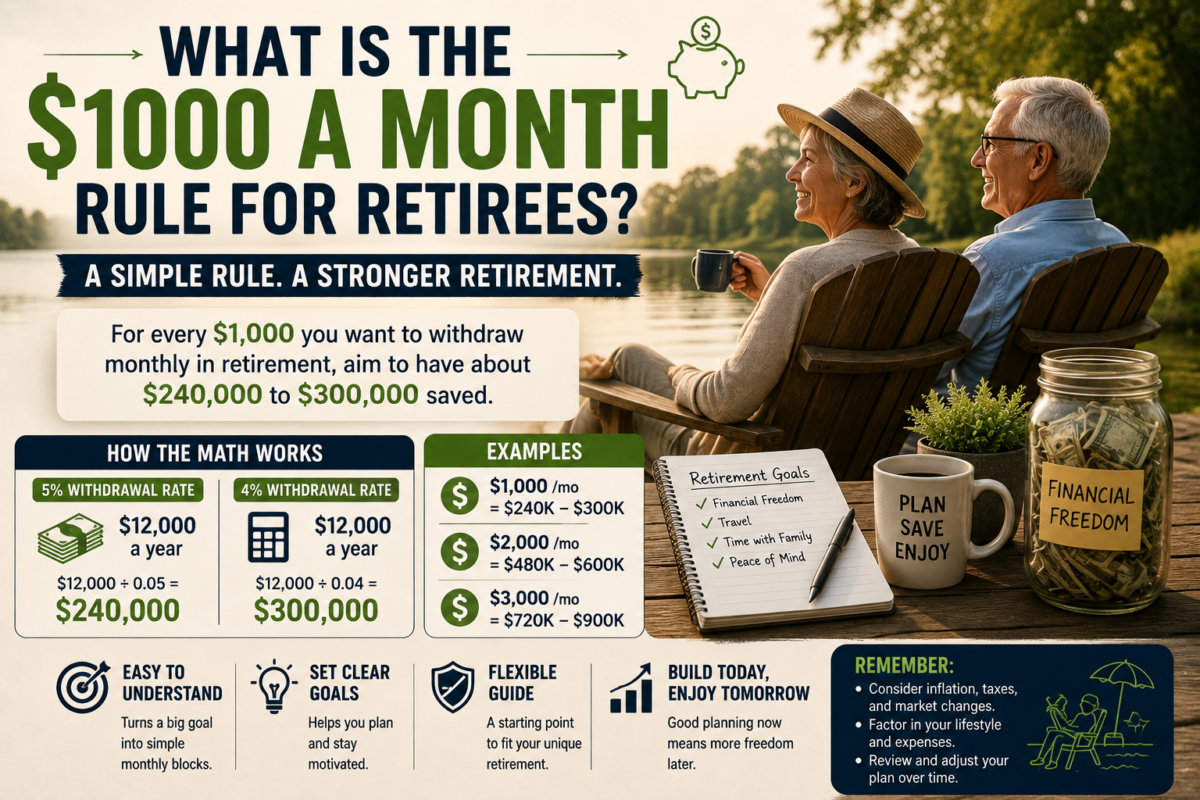
The $1000 a month rule for retirees is a simple way to estimate how much money you may need saved to create steady retirement income. In plain terms, it says that for every $1,000 you want to withdraw each month in retirement, you should aim to have about $240,000 to $300,000 saved, depending on the withdrawal rate used.
Understanding the Rule
This rule is popular because it turns a big retirement goal into a smaller, easier-to-grasp number. Instead of wondering how much money you need for the rest of your life, you can think in monthly income blocks of $1,000.
The idea comes from withdrawal-rate thinking, especially the 4% and 5% rules. A 5% withdrawal rate suggests about $240,000 can produce roughly $1,000 a month, while a more cautious estimate closer to 4% pushes that figure higher, toward $300,000.
In other words, the rule is not about spending exactly $1,000 a month on groceries or bills. It is about building enough retirement savings to generate that amount of income every month.
How The Math Works
The math behind the rule is very straightforward. If you want $1,000 a month, that equals $12,000 a year, and that yearly amount is then matched against a safe withdrawal estimate from your savings.
Using a 5% withdrawal rate, you would divide $12,000 by 0.05, which gives about $240,000. Using a more conservative approach closer to 4%, the number rises because your savings must last longer.
Here are a few simple examples:
- $1,000 a month = about $240,000 to $300,000 saved.
- $2,000 a month = about $480,000 to $600,000 saved.
- $3,000 a month = about $720,000 to $900,000 saved.
This makes the rule useful for quick planning, especially if you want to estimate your retirement target without opening a giant spreadsheet right away.
Why Retirees Use It
Retirees and pre-retirees like this rule because it is easy to remember. It gives a fast answer to a common question: “How much do I need saved to produce the income I want?”.
It also helps people break retirement planning into clear steps. If you know you need $3,000 a month, you can work backward and estimate your savings target instead of guessing.
Another benefit is motivation. A large retirement number can feel scary, but monthly income goals feel more manageable and practical. For many people, thinking in chunks of $1,000 makes the process feel less overwhelming.
What It Does Not Tell You
Even though the rule is helpful, it is still only a rule of thumb. It does not fully account for inflation, market ups and downs, taxes, or how long retirement will last.
It also assumes your retirement money is invested in a way that can support regular withdrawals. If your portfolio is too conservative, too aggressive, or too small, the rule may not fit your real situation.
Your personal spending matters too. A retiree with paid-off housing and low medical costs may need less than someone who is still paying rent, helping family, or traveling often. So the rule should guide your planning, not replace it.
How To Use It
Start by estimating how much monthly income you want in retirement. Then compare that amount with expected income from Social Security, pensions, or other sources.
For example, if you want $3,000 a month but expect $1,500 from Social Security, then your savings only need to cover the other $1,500. That means the $1000 a month rule can help you estimate the savings needed for the remaining income gap.
A simple way to use the rule is this:
- Decide your monthly retirement income goal.
- Subtract guaranteed income sources.
- Multiply the remaining monthly amount by the rule’s savings estimate.
- Review the result as your lifestyle, health, and costs change.
This keeps the math simple while still giving you a practical starting point.
Is It Enough For Retirement
The honest answer is: sometimes, but not always. For some retirees, the rule gives a good starting estimate and feels close to reality.
For others, it can be too simple. Retirement is shaped by living costs, healthcare, travel, debt, family support, and how long your money needs to last. Because of that, two people who both want $1,000 a month may need very different savings plans.
That is why many financial sources treat it as a planning shortcut, not a final answer. It works best when combined with a broader retirement budget and a realistic look at your actual expenses.
A Simple Takeaway
The $1000 a month rule for retirees is a quick planning method that estimates how much savings you need for every $1,000 of monthly retirement income. In most versions, the rule suggests around $240,000 to $300,000 for each $1,000 a month you want to draw in retirement.
It is easy to understand, easy to apply, and useful for setting rough retirement goals. Still, it should be treated as a starting point, not the final word on your retirement needs.